- 1CBAM, the carbon border adjustment mechanism, covers 6 families of imported products.
- 2Above 50 tonnes a year, every tonne imported during the year falls within the mechanism.
- 3Above the threshold, without authorised declarant status, customs blocks clearance.
- 4Imports made in 2026 are paid for by 30 September 2027 at the latest.
A company that imports 30 tonnes of steel screws made in China and 25 tonnes of Turkish aluminium sheets in a year exceeds the 50-tonne threshold. Since 1 January 2026, it has fallen within the European Union's Carbon Border Adjustment Mechanism, CBAM, known as MACF in French. It must obtain authorised declarant status before clearing goods through customs, then declare the carbon emitted to make those products and cover it with certificates.
Am I affected by CBAM?
Answer the 3 questions about your imports: the verdict gives the obligation and the deadline.
The mechanism is set by a European regulation and is one of the environmental obligations for companies that do not depend on company size. In France, the Directorate-General for Energy and Climate (DGEC) processes status applications, and customs checks every import. The price of an imported tonne, which varies by product and country of origin, is set out in our CBAM cost calculation.
1What is CBAM, and why does it exist?
CBAM (Carbon Border Adjustment Mechanism) was created by Regulation (EU) 2023/956 of 10 May 2023. It makes imported products pay the European carbon price, the one European factories in the same sectors already pay, which is separate from the second carbon market that will cover fuels and heating. The importer covers this carbon by buying certificates, 1 per tonne of CO2 equivalent (what a tonne of CO2 represents).
Its purpose is to prevent carbon leakage. The regulation describes this as production moving to countries with less stringent climate rules, or European products being replaced by higher-emitting imports. Emissions then change country without falling, and Europe loses factories.
Until 2025, the Union protected these industries with free allowances: part of their emissions was not charged. CBAM gradually replaces them. As these allowances decline, the share of carbon paid at the border rises, at the same pace for an imported tonne and for a tonne produced in Europe. The consequences for a European site are covered in our CBAM guide for manufacturers.
2Which products does CBAM cover?
Annex I of the regulation lists the products by Combined Nomenclature (CN) code, the customs code on the import declaration. They fall into 6 families: iron and steel, aluminium, cement, fertilisers, electricity and hydrogen. The list goes beyond raw materials: it also covers steel screws and bolts (code 7318), aluminium foil (7607) and ammonia (2814).
The 6 product families subject to CBAM
One photo per family: the customs codes covered, what is counted and whether the 50-tonne threshold applies.
From agglomerated ore to screws and bolts
For each product, the regulation counts embedded emissions, those released in making it. For steel, aluminium, hydrogen and electricity, only the plant's direct emissions count. For cement and fertilisers, the electricity consumed by the plant is added. The calculation follows the logic of a product carbon footprint, on the scope set by the regulation.
Products originating in Iceland, Liechtenstein, Norway and Switzerland are exempted by Annex III. A complete machine, a bicycle or a piece of steel furniture is not covered today.
The list may grow. On 17 December 2025, the Commission proposed adding around 180 customs codes for downstream products, with a high steel or aluminium content, from 1 January 2028. The European Parliament voted on its amendments on 15 September 2026 and negotiations with the Council have opened: this text has not been adopted.
3Who is affected, and above how many tonnes?
The obligation falls on the importer established in the Union, the one who declares the goods to customs for release for free circulation. It can pass to its indirect customs representative, if the representative agrees to act as authorised declarant on its behalf. An importer established outside the Union must use such a representative.
Regulation (EU) 2025/2083, which entered into force on 20 October 2025, created a 50-tonne exemption. An importer whose cumulative net mass of steel, aluminium, cement and fertilisers does not exceed 50 tonnes over the calendar year has no obligation. According to the assessment published by the Commission on 30 September 2026, this threshold would have exempted 0.87% of emissions imported between April 2025 and March 2026, below the 1% limit set by the text.
The threshold has calculation rules, which often decide the outcome:
- Above 50 tonnes, all products combined, every tonne of the year falls within the obligations, including the first 50, as soon as the year's cumulative total crosses the threshold.
- Electricity and hydrogen have no threshold: their importer is affected whatever the quantity imported in the year.
- The threshold applies per importer, whether the goods are declared by the importer itself or by an indirect customs representative on its behalf.
CBAM depends not on the size of the company but on the tonnage it imports.
The foreign supplier has no obligation of its own. It may register its installations in the European registry for the mechanism and give its customers the actual emissions of its plants, calculated like an industrial site carbon footprint and then verified by an accredited CBAM verifier. Without them, the importer applies default values, set out in our CBAM cost calculation.
4What is an authorised CBAM declarant?
The authorised CBAM declarant is the only party that may import these products above the threshold (Article 4 of the regulation). This status, granted to the importer or its indirect customs representative, opens an account for its holder in the European registry for the mechanism.
How do you obtain the status?
The application is filed in the European registry, before the first import, and the competent authority of the Member State processes it: in France, the DGEC (in French). Once approved, the status takes the form of a CBAM account number, of the type CBAM-FR-2026-..., which every customs declaration must carry. A company established for less than 2 financial years also provides a bank guarantee equal to the estimated value of the certificates it will have to surrender.
Importers that filed their application by 31 March 2026 at the latest may import provisionally while awaiting the decision. The others must wait for their status. On 7 January 2026, according to the Commission, more than 12,000 companies in the Union had applied for the status, and more than 4,100 had obtained it.
What must the declarant do next?
The status brings 4 obligations, whose dates the 2025 omnibus regulation set:
- Each year, by 30 September at the latest, it files in the registry the declaration of the quantities imported the previous year and their emissions, the first time in 2027 for 2026.
- On the same date, it surrenders as many certificates as declared emissions, after deducting the share still covered by free European allowances.
- It buys these certificates from the Member States, on a common platform, from 1 February 2027. Their price follows the European carbon price: a quarterly average for imports made in 2026, then a weekly average.
- From 2027, at the end of each quarter it holds certificates covering at least 50% of the emissions imported since 1 January.
A certificate not surrendered by 30 September incurs the fine of the European carbon market, and an importer that exceeds the threshold without status risks 3 to 5 times more, as set out in the fines chapter of our cost calculation.
5What is the role of customs in CBAM?
Customs is the control point of the mechanism. Since 1 January 2026, Article 25 of the regulation has prohibited it from authorising import by anyone other than an authorised declarant, except for the exemption below the threshold. It also sends the Commission, for each declaration, the importer's EORI (economic operator registration and identification) number, its account number, the CN code, the quantity and the country of origin. The Commission then cross-checks these data against the registry.
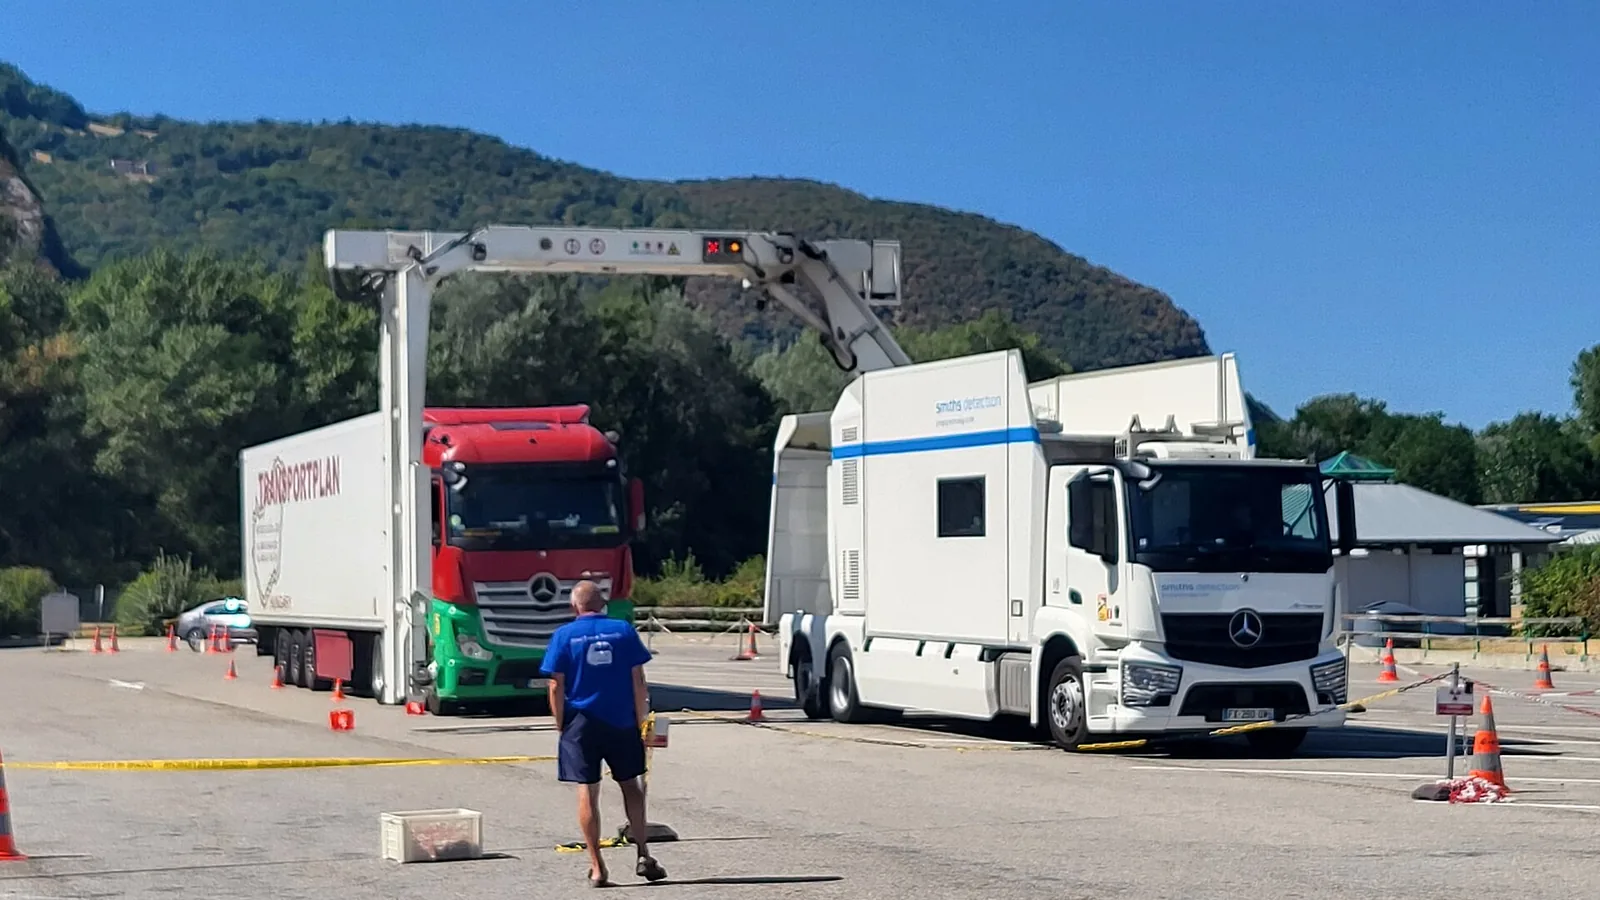
In France, status verification is automated within customs clearance, according to French customs (DGDDI) (in French). The declaration must carry the EORI linked to the importer's SIREN (its French company identification number), the one used in its status application: an EORI linked to a SIRET (the identification number of a single establishment) blocks the goods. A code tells the system about the importer's or the goods' situation:
- Code Y128 signals an importer that holds the status. It uses it from its first import of the year, with its account reference, without waiting to exceed 50 tonnes.
- Code Y238 signals an application filed before 31 March 2026 and still being processed. Since 1 April 2026 (in French), it no longer covers an application filed later.
- Code Y137 signals an importer that does not expect to exceed 50 tonnes in the year and declares the exemption on each import.
- Code Y134 signals goods originating in an exempted territory, such as Switzerland or Norway.
An importer that discovers during the year that it will exceed the threshold files its application without waiting. If it exceeds the threshold without status, the competent authority records this in a decision that it notifies to customs, and the importer must obtain the status before any new import (Article 25a). The entry check is similar to that of the EU Deforestation Regulation (EUDR), which also relies on the customs declaration.
6What should you do, and by when?
The mechanism comes into force in stages, and the timeline below distinguishes the text in force from what the Commission is proposing. For an importer, 2026 is a counting year. It clears goods under its status and gathers, line by line, the quantities, CN codes, countries of origin and actual emissions it obtains from its suppliers. Accredited verifiers can only register from 1 September 2026, and the DGEC advises estimating the year's costs on default values.
CBAM deadlines and the end of free allowances
The deadlines drawn to a time scale. Dotted: the Commission's proposal, not adopted.
Deadlines · 30 September 2027
First annual declaration and surrender of certificates
Deadline to declare 2026 imports and surrender the corresponding certificates. The deadline recurs every 30 September; from 2027, the declarant must also hold certificates covering 50% of the year's emissions at the end of each quarter.
The number of certificates to surrender depends on the gap between the product's emissions and the level of a high-performing European producer, as set out in our cost-per-tonne calculation.
The text in force removes free allowances for CBAM sectors in 2034, which pushes the bill up each year until then. The Commission proposal of 17 July 2026 would push this end back to 2038, with the factor remaining at 15% from 2034 to 2037. Environment ministers discussed it on 12 October 2026 without a decision: the 2034 timetable prevails until it is adopted.
The first CBAM bill is settled in 2027 and prepared with the 2026 customs declarations.
At Projet Celsius, we think the first thing to do in 2026 is to go back over the year's customs declarations and sort them by CN code and by country of origin. This table shows whether the 50-tonne threshold is crossed, which lines weigh most and which suppliers to approach for actual emissions instead of default values before September 2027. The same data feeds the Scope 3 of the Bilan Carbone® (the French carbon accounting method), the sustainability statement and the company's transition plan.
7Key takeaways
- CBAM, known as MACF in French, makes the European importer pay for the carbon emitted outside the Union to make steel, aluminium, cement, fertilisers, electricity and hydrogen.
- Above 50 tonnes a year of these products, electricity and hydrogen aside, every tonne of the year falls within the mechanism.
- Since 1 January 2026, authorised declarant status is required to clear goods through customs, and customs checks it automatically on every import.
- Imports made in 2026 are declared and paid for in certificates by 30 September 2027 at the latest, with purchases possible from 1 February.
- European free allowances disappear in 2034 under the text in force; the 2038 date is only a proposal.
To put a figure on what these rules cost per imported tonne, product by product and country by country, see our CBAM cost calculation.