- 1ESRS E1 has 11 disclosure requirements, from the transition plan to the financial effects.
- 2An emissions assessment fills 2, energy and emissions, and prepares 3 others.
- 3Electricity is reported in 2 ways: by grid location and by purchase contracts.
- 4Carbon credits are never deducted from emissions: they are published separately.
ESRS E1, the climate standard within the European Sustainability Reporting Standards (ESRS), sets what a company subject to the CSRD publishes on climate change in its sustainability statement. It applies as soon as climate is a material issue for the company, which is decided by the double materiality assessment (its method, step by step). This was the case for 99% of companies in the 905 reports for the 2025 financial year analysed by EFRAG (the European Financial Reporting Advisory Group), the body that prepares these standards for the European Commission. The revised version, published in the Official Journal of the European Union on 21 September 2026, has 11 disclosure requirements.
CSRD climate requirements and what a Bilan Carbone® contributes
Choose a requirement: what must be disclosed and what an emissions assessment contributes.
E1-8 - Scope 1, 2 and 3 emissions
Metrics and targets; 2023 number: E1-6
To publish
Emissions in tCO2e: Scope 1 and its share under the EU emissions trading system, Scope 2 location-based and market-based, Scope 3 by significant category.
What the assessment gives
It is the inventory itself, by GHG Protocol or ISO 14064-1 category, with biogenic CO2 reported separately.
That version, laid down by Delegated Regulation (EU) 2026/1563, applies to financial years beginning on or after 1 January 2027. For the 2026 financial year, a company may keep the 2023 version, whose requirements carried different numbers, or move to the new one early: our article on the revised ESRS compares these options. Once transposed into French law, by 19 March 2027 at the latest, the Omnibus Directive will limit the CSRD to companies with more than 1,000 employees and €450 million turnover. Our guide to the CSRD after Omnibus sets out who is affected.
1How is the CSRD climate standard structured?
The standard sets its objective in its first paragraphs. The information published must make it possible to understand whether the company's strategy is compatible with 1.5°C of warming, as provided for by the Paris Agreement, and with the EU's climate neutrality in 2050. It covers 3 sub-topics, mitigation, adaptation and energy, and 7 greenhouse gases, from CO2 to nitrogen trifluoride.
The 11 requirements fall into 3 blocks. Strategy brings together the transition plan, the identification of climate risks and the resilience of the business model. Management covers policies, then actions and their resources. The last block, metrics and targets, brings together the figures: targets, energy, emissions, carbon credits, internal carbon price and anticipated financial effects.
The revision changed the numbering. Scope 1, 2 and 3 emissions, published as E1-6 in the 2023 version, move to E1-8, and targets move from E1-4 to E1-6. Risk identification and resilience, which were attached to the general standard ESRS 2, become requirements E1-2 and E1-3. Only the transition plan keeps its number, E1-1.
2What must be published on the transition plan and targets?
The transition plan, requirement E1-1, is described by its main characteristics: its reduction objectives, its decarbonisation levers, its key actions, the investments that fund it and its approval by the management bodies. The company adds the assumptions it depends on, an assessment of the emissions locked in by its assets and products, and the progress made. It also publishes its investments for the year in coal, oil and gas.
A company that has no plan says so, and states whether it intends to adopt one and by when. If its plan's targets are not compatible with 1.5°C, it must explain this in its report, placing its values against the reference pathway. For the 2025 financial year, 69% of companies analysed by EFRAG reported a transition plan, against 55% a year earlier.
A company may publish without a transition plan, as long as it says so and states whether it intends to adopt one.
Policies, requirement E1-4, follow the framework common to all the standards. Actions, requirement E1-5, are presented by decarbonisation lever, with the reductions already achieved and those expected. Targets, requirement E1-6, are published as follows, without repeating the errors found on climate targets:
- Reduction targets cover Scopes 1, 2 and 3, separately or combined, in absolute terms and, where applicable, as intensity.
- Where a target does not cover the whole inventory, the company states the share of each scope it covers and the gases concerned.
- The company states whether its targets are science-based and compatible with 1.5°C, with the framework and method used, such as a sector pathway.
The method of the Science Based Targets initiative (SBTi) is one of these frameworks: our guide to SBTi for an industrial SME details the steps.
3Which emissions and energy must be reported?
Requirement E1-7 asks for the total energy consumption of the company's own operations, in megawatt-hours (MWh), broken down by fossil, nuclear and renewable sources. Companies in high climate impact sectors also give a detailed breakdown of fossil energy: coal, oil, natural gas, and purchased electricity and heat of fossil origin. A company that produces energy reports its renewable and non-renewable production separately.
Requirement E1-8 covers the emissions inventory, in tonnes of CO2 equivalent (tCO2e). The standard refers to the GHG Protocol, the international carbon accounting standard, and also admits ISO 14064-1 (2018). The default boundary is financial control, that of the consolidated accounts, and the other GHG Protocol approaches remain admissible. The company publishes 3 blocks of emissions:
- Scope 1, the company's direct emissions, with the share emitted by installations covered by the EU Emissions Trading System.
- Scope 2, purchased energy, as 2 figures: one location-based, using the average grid factor, the other market-based, using purchase contracts (GHG Protocol guidance).
- Scope 3, the value chain, for each significant category, with the total and the breakdown by category, using the 15 GHG Protocol categories or those of ISO 14064-1.
In its report for 2024, Danone thus publishes a Scope 2 of 694,742 tCO2e location-based and 122,408 tCO2e market-based. The revised version no longer asks for the total of the 3 scopes or emissions intensity per unit of turnover, which the 2023 version required.
Biogenic CO2, emitted by burning wood or other biomass, is reported separately from Scope 1. For Scope 3, the standard asks the company to estimate all categories first, the 15 GHG Protocol categories or those of ISO 14064-1, and then select those that are significant. Significant categories are updated every year, and the full Scope 3 inventory at least every 3 years, a pace that ties in with the question of redoing a carbon footprint assessment every year.
Examples of emissions to report, from the boiler to the forest
For each source, what the European standard asks for and the share already covered by the regulatory assessment.
Boilers and furnaces - Scope 1
What ESRS E1 requires
Direct emissions in tCO2e, with the share coming from installations covered by the EU emissions trading system, calculated using the method of that system.
What an assessment already does
The direct emissions category gives the total. The share covered by allowances can be drawn from the annual declarations these sites already make.
4What about carbon credits, internal carbon pricing and risks?
5 other requirements ask for information that no inventory contains: carbon credits (E1-9), the internal carbon price (E1-10) and the company's exposure to the effects of climate change (E1-2, E1-3 and E1-11).
Removals and carbon credits (E1-9)
The standard excludes all removals and carbon credits from the calculation of emissions. Requirement E1-9 has them published separately: the company's removal and storage projects, then the credits cancelled during the year, those purchased and not yet cancelled, and the share coming from removal projects. A company that calls itself carbon neutral thanks to credits must explain why they do not hold back progress on its targets, a subject covered in our article on carbon neutrality for companies.
Internal carbon pricing (E1-10)
An internal carbon price assigns a value to each tonne emitted in the company's decisions. Requirement E1-10 asks whether and how this price is used, in investments, transfer pricing or scenarios, and the average price per tonne of each pricing system. The company also checks that it is consistent with the prices used in the impairment tests in its accounts. In the reports for the 2024 financial year analysed by EFRAG, 20% of companies used such a price.
Climate risks and their financial effects (E1-2, E1-3, E1-11)
The company classifies each material climate risk as a physical risk, such as a flood or a heatwave, or a transition risk, such as a change in regulation or in the market. If it carries out a scenario analysis, it states whether it used at least one high-emissions scenario for physical risks, and at least one scenario compatible with 1.5°C for transition risks. From this it draws an assessment of the resilience of its business model.
Requirement E1-11 puts these risks into euros: the value of exposed assets, the share covered by adaptation or mitigation actions, the turnover exposed, assets that could lose value, and opportunities. The standard gives a phase-in period for most of these amounts: until the 2027 financial year for companies that already report, and their first 2 financial years for a company entering the CSRD. The value of exposed assets and the share covered are published from the first report. The map of the exposure of municipalities (communes in French) in 2050 gives an idea of the hazards a site analysis should look at.
5Is a Bilan Carbone® enough for ESRS E1?
No, but it supplies the quantified basis. The CSRD requires no named method and, in our reading of the standard, the inventory from a Bilan Carbone® (the French carbon accounting method) or the GHG Protocol provides the emissions and energy data, which is 2 of the 11 requirements. It also prepares the transition plan, the actions and the targets, which start from it. The Association pour la transition Bas Carbone, which maintains the method, considers that a Bilan Carbone® approach followed through to the Advanced level meets most of the 2023 ESRS E1. That approach goes beyond the inventory, since it includes the transition plan and the risk analysis.
The 2022 French regulatory method uses the 6 categories of ISO 14064-1, and its Annex 7 publishes a correspondence table with the items of the Bilan Carbone® and the GHG Protocol.
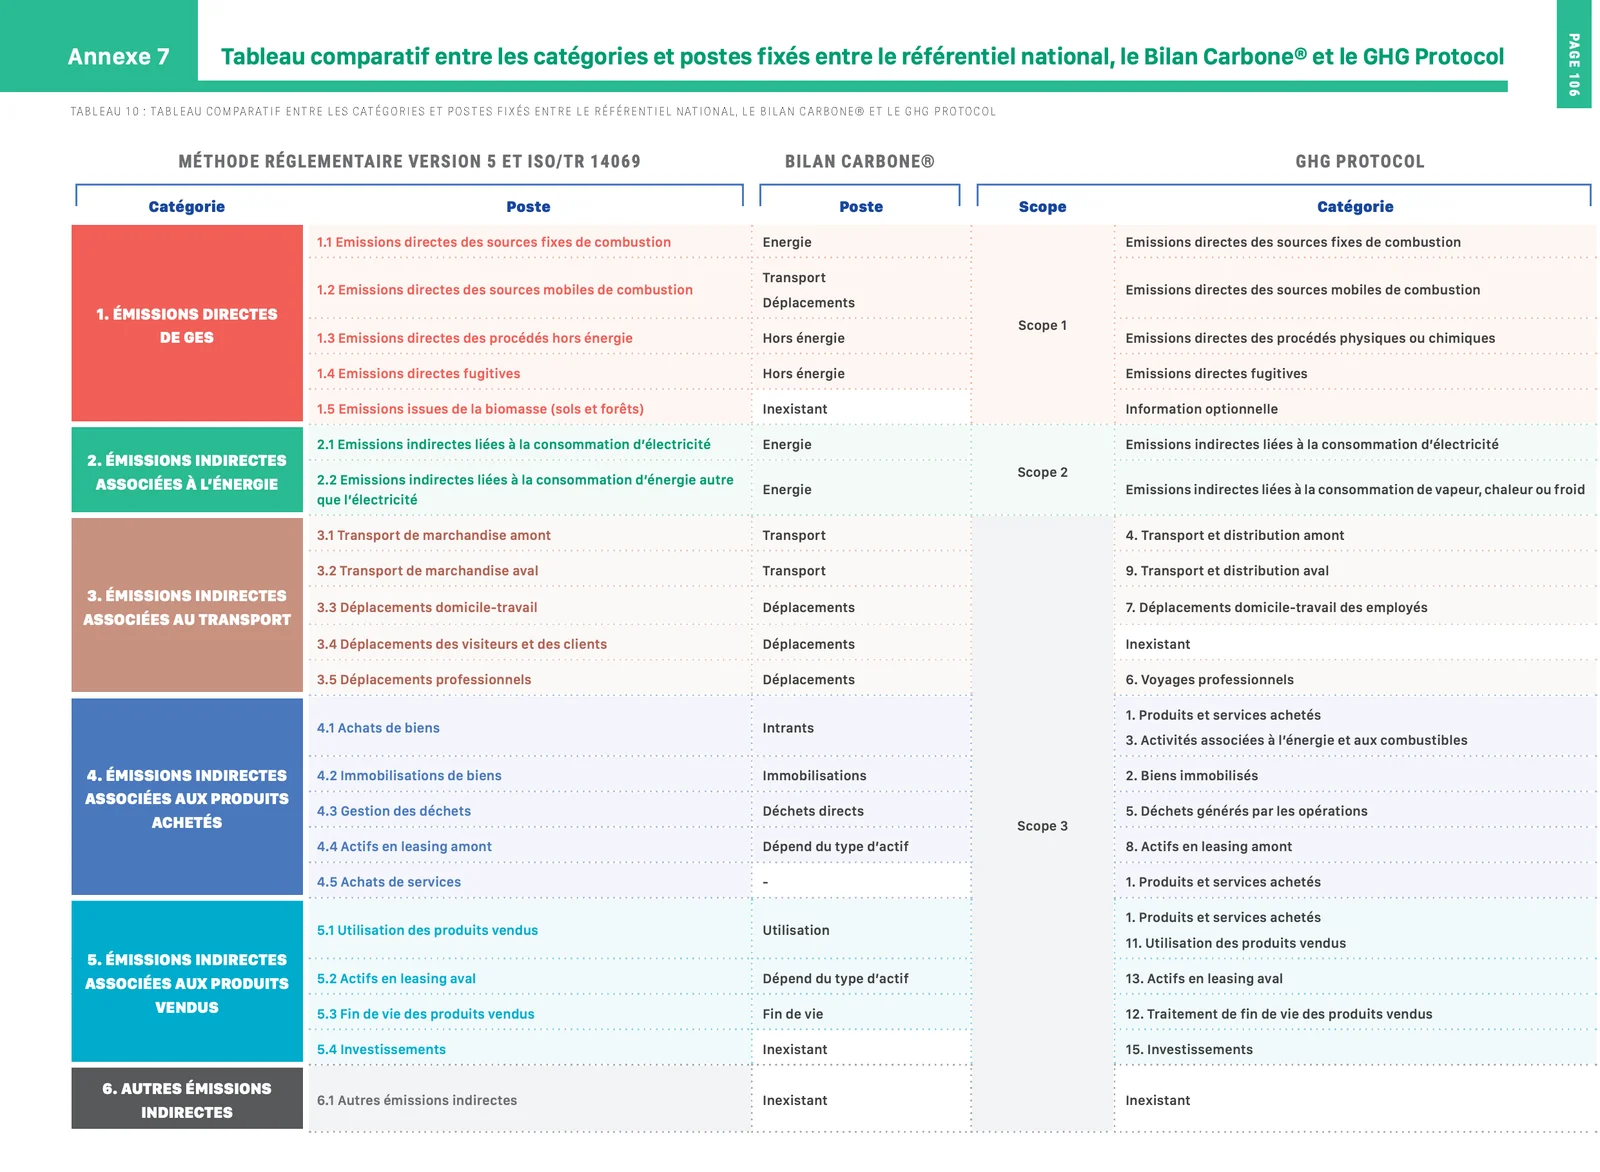
Annex 7 of the regulatory method sets its 6 categories and 22 items against the Bilan Carbone® and the GHG Protocol. Category 1 becomes Scope 1, category 2 becomes Scope 2, and categories 3 to 6 become Scope 3. Item 4.1, purchases of goods, is split between GHG Protocol categories 1 and 3, and travel by visitors and customers has no equivalent there. The standard admits the ISO 14064-1 categories: this table is only for companies that choose those of the GHG Protocol. The table dates from 2022: it covers neither market-based Scope 2 nor data centres.
To move from a regulatory assessment to the format of requirement E1-8, 4 points have to be reworked or decided:
- Market-based Scope 2 has to be calculated in addition, because the French method imposes the average grid factor and prohibits any other factor.
- Indirect emissions can keep the ISO 14064-1 categories, which the French method follows, or move to the 15 GHG Protocol categories, the standard's primary reference, using the correspondence table.
- Scopes 1 and 2 are split between the consolidated accounting group and the rest, and the choice of boundary, which the French method sets by default at operational control, is disclosed.
- Data centre and cloud computing services are separated from other purchases, as a sub-category of goods and services purchased.
The rest comes out of no emissions inventory: risks and scenarios, resilience, policies, carbon credits, the internal price and financial effects, which is 6 requirements out of 11. In France, however, the sustainability statement can exempt a company from the regulatory emissions assessment (BEGES, France's mandatory greenhouse gas emissions report): Article L. 229-25 of the Environmental Code, amended by the Law of 30 April 2025, allows this when the statement publishes an emissions assessment and a transition plan, and the assessment describes the activities carried out in France.
The published figures are verified under limited assurance by a statutory auditor or an independent third-party body, as for an assessment carried out in-house and then verified.
An emissions assessment fills the numerical lines of ESRS E1, but half of the standard sits elsewhere, in strategy and the accounts.
For us at Projet Celsius, the right order is to build the next assessment in the E1-8 format. Scope 2 is calculated by 2 methods, Scope 3 in the 15 GHG Protocol categories, the standard's primary reference, and biogenic CO2 and credits stay separate. The same inventory then serves the sustainability statement, the regulatory assessment and the targets. Physical risks and their financial effects call for a separate piece of work, to be started with the finance department, because they are quantified in the accounts.
6Key takeaways
- The revised ESRS E1 has 11 disclosure requirements, mandatory for financial years beginning on or after 1 January 2027, and available for early application from 2026.
- The inventory from a Bilan Carbone® or the GHG Protocol fills 2 requirements, energy and emissions, and prepares the transition plan, the actions and the targets.
- Electricity is reported by location and by market, whereas the French regulatory method admits only the average grid factor.
- Removals and carbon credits are never deducted from emissions: they are published separately, with the justification of any neutrality claim.
- Climate risks, resilience and financial effects require work with the finance department, which no emissions assessment replaces.
To choose which version of the standards to apply for the 2026 financial year, our article on the revised ESRS details the 3 options opened by the regulation.
- Standards: Delegated Regulation (EU) 2026/1563 of 3 July 2026, OJ L of 21 September 2026, Articles 2 and 3, Annex I, ESRS E1 (paragraphs 1 to 42, AR 2, 19 to 24) and ESRS 1 (paragraphs 125 to 127); Delegated Regulation (EU) 2023/2772, Annex I, ESRS E1 in its 2023 version.
- Directive: Directive (EU) 2026/470 of 24 February 2026, known as Omnibus, OJ L of 26 February 2026, recital 5 (removal of the reasonable assurance standards).
- Bilan Carbone® method: Association pour la transition Bas Carbone, method wiki, § 6.2, compatibility with the CSRD.
- Calculation methods: GHG Protocol, Corporate Accounting and Reporting Standard, 2004; GHG Protocol, Scope 2 Guidance, 2015; Ministry of Ecological Transition, method for carrying out greenhouse gas emissions assessments, version 5, July 2022, pp. 9, 15, 24 and 45.
- Published reports: EFRAG, State of Play 2026, July 2026, pp. 4, 10 and 18; EFRAG, State of Play 2025, July 2025, p. 6; Danone, 2024 universal registration document, p. 218, gross and total GHG emissions.
- France: Law No. 2025-391 of 30 April 2025, Article 10, which inserts into Article L. 229-25 of the Environmental Code the exemption from the emissions assessment for companies that publish a sustainability statement. The pages of Légifrance (the French government's official legal database) are in French.